Published
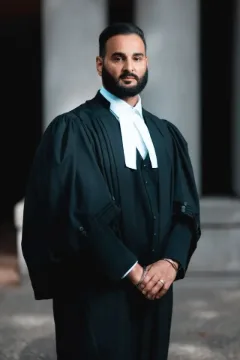
Sundeep S. Grewal is a lawyer at Lawgical Law Corporation, called to the BC bar in 2018, and a member of the Law Society of British Columbia.
Updated November 11, 2026: the Income Tax Act filing rules for estates, as discussed in the CLE probate manual, checked that day.
The estate is a separate taxpayer. It files a T3 Trust Income Tax and Information Return for each taxation year after death.
Deadline: 90 days after the estate’s year-end, and 90 days isn’t the same as three months.
Graduated rate estate: for up to 36 months after death, the estate can be designated a graduated rate estate, with tax advantages.
The lawyers who handle these estate files
About our lawyers
Sundeep S. Grewal founded Lawgical Law Corporation and practises probate, estate litigation and immigration. He has represented clients in the Provincial and Supreme Courts of British Columbia, from chambers applications to contested trials.
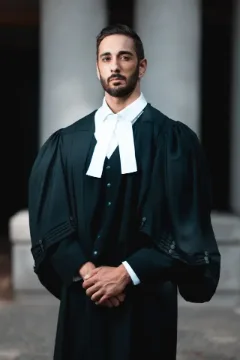
Pardeep S. Grewal is a probate, estates and immigration lawyer known for clear communication and practical strategy.
After someone dies, there are two kinds of tax return. The deceased’s final T1 return covers income up to the date of death. After that, the estate itself is a separate taxpayer, and the executor files a T3 Trust Income Tax and Information Return for each of the estate’s taxation years, covering income the estate earns, such as interest, dividends, rent and gains on assets sold during administration. The filing deadline is 90 days after the estate’s year-end, which isn’t always three calendar months. For the first 36 months after death, the estate can be designated a graduated rate estate (GRE), which gives it access to graduated tax rates and other benefits, and only a GRE can choose a year-end other than December 31. Late filing brings penalties. Most executors work with an accountant on the T3, but the executor is responsible for making sure it’s filed.
Lawgical Law Corporation, a probate and estate law firm with offices in Surrey, Abbotsford and Vancouver, BC, coordinates with executors’ accountants on estate tax filings and clearance; this guide is by Sundeep S. Grewal.
Leave your details and our team will contact you to arrange a time with a lawyer. Or call (778) 598-3785.
Thank you, we have your request
A member of our team will contact you to arrange a time. If your matter is urgent, call us at (778) 598-3785, Monday to Friday, 9:00 am – 5:00 pm.
When a T3 is filed
| Situation | Filing |
|---|---|
| Estate finished within a year of death | A “first and final” T3, due 90 days after administration is completed |
| Estate continues past a year | A T3 for each taxation year, each due 90 days after year-end |
| Income allocated to beneficiaries | A T3 Summary and T3 slips for the beneficiaries, also due 90 days after year-end |
The rules on which trusts must file changed for taxation years ending after December 30, 2023; check the current CRA T3 guide (T4013) with your accountant.
Graduated rate estate
- For up to 36 months after death, the estate can be designated a GRE.
- An estate that isn’t a GRE pays tax at the top marginal rate and loses many other favourable rules.
- Only a GRE can choose a year-end other than December 31, and only during the 36 months.
- A person has only one estate for tax purposes, even with multiple wills.
Choosing the year-end
A GRE can choose any year-end within the first year after death. December 31 is simpler, because financial institutions issue slips for the calendar year, but an off-calendar year-end can defer tax and avoid the busy tax season. Discuss the choice with your accountant at the start.
Late filing
If the T3 is late and tax is owing, the penalty is 5% of the unpaid tax plus 1% for each full month late, up to 12 months. If no tax is owing because the income was paid to beneficiaries, a late T3 Summary still attracts a separate penalty of $25 a day, with a minimum of $100 and a maximum of $2,500.
Clearance before distribution
Before the final distribution, the executor should get a CRA clearance certificate covering the final T1 and T3 returns, or risk personal liability. See the final tax return and clearance certificate and executor personal liability.
Mistakes I have seen
- Filing only the final T1 and forgetting the estate’s own T3s.
- Counting “three months” instead of 90 days and filing late.
- Missing the GRE designation, so the estate is taxed at the top rate.
Frequently asked questions
Do all estates need a T3 return?
Not always. It depends on the estate’s income and the current filing rules. Even if none is required, beneficiaries should get a statement of income allocated to them.
Can the T3 be filed online?
T3 returns can generally be e-filed with the CRA unless an exclusion applies.
Who signs the T3?
The executor or administrator, as the estate’s legal representative.
What should I do right now?
Engage an accountant, decide the estate’s year-end, and diarize the 90-day filing dates.
Book a consultation with our probate lawyers in Surrey, Abbotsford or Vancouver.
Ready to book? Open the booking form ↑
Sources
- Income Tax Act, R.S.C. 1985, c. 1 (5th Supp.), ss. 150(1)(c), 162, 248(1), as discussed in CLE BC, Probate and Estate Administration Practice Manual, §§12.32–12.35, 13.21
- T4013 T3 Trust Guide, Canada Revenue Agency
This article is general information about BC law, not legal advice for your situation.