Published
Sundeep S. Grewal is a lawyer at Lawgical Law Corporation, called to the BC bar in 2018, and a member of the Law Society of British Columbia.
Updated November 11, 2026: the Canada Revenue Agency’s clearance certificate page (modified January 20, 2026), its guide for deceased persons (T4011) and the Wills, Estates and Succession Act (s. 155) checked that day.
Final return due: April 30 of the next year if death was between January and October; 6 months after death if it was in November or December. Later dates apply if the deceased or their spouse ran a business.
Clearance certificate: ask the CRA for one (Form TX19) after all returns are assessed and paid, and before the final distribution. The assessment “can take up to 120 days”.
Why it matters: an executor who distributes without one is “personally liable for unpaid amounts, up to the value of the amount of assets distributed”.
The lawyers who handle these estate files
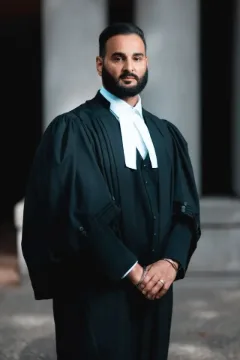
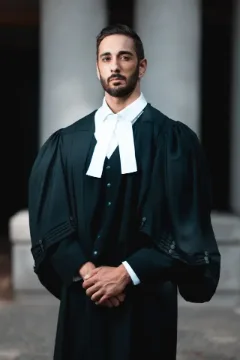
About our lawyers
Sundeep S. Grewal founded Lawgical Law Corporation and practises probate, estate litigation and immigration. He has represented clients in the Provincial and Supreme Courts of British Columbia, from chambers applications to contested trials.
Pardeep S. Grewal is a probate, estates and immigration lawyer known for clear communication and practical strategy.
An executor in BC has to deal with the deceased person’s taxes before the estate is fully paid out. That means filing the final income tax return for the year of death, any earlier returns that were never filed, and, if the estate earns income after death, a T3 trust return for the estate. Once every return has been assessed and the tax is paid, the executor asks the Canada Revenue Agency for a clearance certificate, which confirms that the deceased and the estate owe nothing more. Holding back enough money until that certificate arrives protects the executor: if they distribute everything first and the CRA later finds tax owing, the executor can be personally liable for it, up to the value of what they distributed.
Lawgical Law Corporation, a probate and estate law firm with offices in Surrey, Abbotsford and Vancouver, BC, guides executors through probate, the tax steps and final distribution; this guide is by Sundeep S. Grewal.
Leave your details and our team will contact you to arrange a time with a lawyer. Or call (778) 598-3785.
Thank you, we have your request
A member of our team will contact you to arrange a time. If your matter is urgent, call us at (778) 598-3785, Monday to Friday, 9:00 am – 5:00 pm.
An executor’s tax steps, in order
- Tell the CRA about the death and cancel or redirect benefits.
- Gather the slips: T4s, T5s, RRSP and RRIF slips, pension slips, and the values of capital property at the date of death.
- File any unfiled returns for earlier years.
- File the final return for the year of death, and any optional returns.
- File T3 returns for income the estate earns after death, if required.
- Pay the tax and wait for the notices of assessment.
- Apply for the clearance certificate (Form TX19).
- Make the final distribution once the certificate arrives, and not before 210 days after the grant unless everyone required consents (WESA s. 155).
The final return: what goes on it, and when it’s due
| Date of death | Final return and balance due |
|---|---|
| January 1 to October 31 | April 30 of the following year |
| November 1 to December 31 | 6 months after the date of death |
| The deceased or their spouse carried on a business, death January 1 to December 15 | Return due June 15 of the following year (balance still due April 30) |
The final return covers income from January 1 to the date of death. It also includes amounts that arise because of the death, mainly:
- Capital gains on deemed disposition: capital property is treated as sold at fair market value immediately before death, unless it passes to a spouse or partner.
- RRSPs and RRIFs: generally the full value, unless they pass to a spouse or partner or a financially dependent child or grandchild. See TFSA, RRSP and life insurance on death.
Optional returns can sometimes reduce the total tax by splitting certain income onto separate returns, such as a return for “rights or things” (amounts owed to the deceased but not yet paid at death). The estate’s accountant decides whether they help. For the bigger picture, see is there inheritance tax in Canada?
The estate’s own return (T3)
After death, the estate is a separate taxpayer. If it earns income, such as interest, rent or dividends, before it is distributed, the executor files a T3 return “to report the income the estate earned after the date of death” (CRA guide T4011). An estate can qualify for special tax treatment as a graduated rate estate for up to 36 months after the death. A T3 isn’t always needed, for example when the estate is distributed right away.
The clearance certificate: how to get one
The CRA says to request the certificate only after you have filed the required returns and received the notices of assessment, and after all tax, interest and penalties are paid or secured. Don’t send the request with the returns (CRA, Apply for a clearance certificate). With Form TX19 you include:
- a signed copy of the will and the probate documents (or the document appointing the administrator);
- proof that you are the legal representative;
- a list of assets at the date of death, with their adjusted cost base and fair market value at distribution;
- a statement of distributions made so far and a plan for the rest; and
- the names, addresses and tax numbers of beneficiaries receiving property other than cash.
You can submit it online through Represent a Client, or by mail or fax. The CRA sends an acknowledgement within 45 days, and the assessment “can take up to 120 days, assuming all of the necessary documents were provided”.
How much to hold back
An executor can usually make an interim distribution once the 210 days have passed, but should keep back enough to cover the estimated tax, the accountant’s and legal fees, and a cushion, until the clearance certificate arrives. The estate’s accountant can estimate the figure. Explain the holdback to the beneficiaries in writing; it is one of the most common reasons they think an executor is taking too long.
Mistakes I have seen
- Paying out the whole estate, then receiving a reassessment the executor has to pay personally.
- Forgetting the tax on an RRSP or RRIF that went to a named beneficiary, so the estate is short.
- Sending the TX19 with the final return, before it has been assessed.
- Missing earlier years the deceased never filed.
Frequently asked questions
Is a clearance certificate mandatory?
It isn’t required by law, but without one the executor can be personally liable for unpaid tax up to the value of what they distributed. Most executors get one before the final distribution.
Who signs the final return?
The executor or administrator, as legal representative of the deceased.
What if the deceased hadn’t filed taxes for years?
The executor must file the missing returns. Get the estate’s accountant involved early, as interest and penalties may apply.
Is the CPP death benefit taxable?
Yes. It is taxed to the beneficiary who receives it in the year, or to the estate if it isn’t paid out to a beneficiary that year (CRA guide T4011).
Do I need probate before dealing with the CRA?
No grant is needed to file the final return, but the CRA asks for the probate documents with the clearance certificate request.
What should I do right now?
Write down the final return deadline for the date of death, gather last year’s return and this year’s slips, and bring in an accountant. Then plan your holdback before any distribution.
Book a consultation with our probate lawyers in Surrey, Abbotsford or Vancouver.
Ready to book? Open the booking form ↑
Related guides: the T3 estate return
Sources (official)
- Apply for a clearance certificate, Canada Revenue Agency (modified January 20, 2026)
- Preparing Returns for Deceased Persons (T4011), Canada Revenue Agency
- Wills, Estates and Succession Act (s. 155), BC Laws
This article is general information, not legal or tax advice for your situation. Speak to an accountant about the estate’s tax returns.