Published
Sundeep S. Grewal is a lawyer at Lawgical Law Corporation, called to the BC bar in 2018, and a member of the Law Society of British Columbia.
Updated November 11, 2026: the Canada Revenue Agency’s pages on non-taxable amounts (modified September 17, 2026) and its guide for deceased persons (T4011), the Prime Minister’s March 21, 2025 announcement on the capital gains inclusion rate, and BC’s Probate Fee Act checked that day.
Short answer: no. Canada and BC have no inheritance tax. The CRA lists “most gifts and inheritances” among amounts you don’t report as income.
But the estate can owe tax. The deceased is treated as having sold their capital property at death, and the full value of an RRSP or RRIF is usually income on their final return. That tax is paid by the estate before you inherit.
And BC charges probate fees, about 1.4% of an estate’s value above $50,000.
The lawyers who handle these estate files
About our lawyers
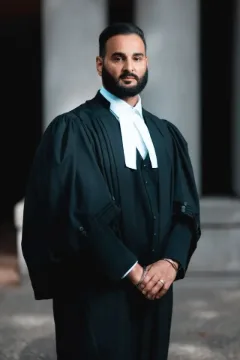
Sundeep S. Grewal founded Lawgical Law Corporation and practises probate, estate litigation and immigration. He has represented clients in the Provincial and Supreme Courts of British Columbia, from chambers applications to contested trials.
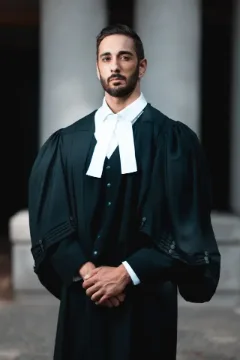
Pardeep S. Grewal is a probate, estates and immigration lawyer known for clear communication and practical strategy.
There is no inheritance tax in Canada or in British Columbia. If you inherit money or property, you don’t pay tax on receiving it, and you don’t report it as income. The tax happens earlier, inside the estate. When a person dies, the Income Tax Act treats them as having sold their capital property, such as a cottage, rental property or shares, at its fair market value just before death, and taxes the gain on their final return. Registered plans like RRSPs and RRIFs are usually added to that final return in full. The executor pays that tax from the estate, and BC adds probate fees on top. What you receive is what is left after those are paid.
Lawgical Law Corporation, a probate and estate law firm with offices in Surrey, Abbotsford and Vancouver, BC, guides executors through probate and the steps to clear an estate’s taxes; this guide is by Sundeep S. Grewal.
Leave your details and our team will contact you to arrange a time with a lawyer. Or call (778) 598-3785.
Thank you, we have your request
A member of our team will contact you to arrange a time. If your matter is urgent, call us at (778) 598-3785, Monday to Friday, 9:00 am – 5:00 pm.
What is taxed when someone dies in Canada?
| Item | What happens | Who pays |
|---|---|---|
| Inheritance you receive | Not taxable income (CRA: “most gifts and inheritances”) | No one |
| Capital property (rental property, cottage, shares, investments outside registered plans) | Deemed sold at fair market value immediately before death; the gain goes on the final return | The estate |
| RRSP or RRIF | Full value usually included in the final return, unless it goes to a surviving spouse or common-law partner (or, in some cases, a financially dependent child or grandchild) | The estate, usually |
| TFSA | Growth up to the date of death is tax-free; income after death can be taxable to the beneficiary | Usually no tax on the death itself |
| Principal residence | The gain is usually sheltered by the principal residence exemption, for the years it qualified | Usually none |
| Property left to a surviving spouse or common-law partner | Can usually pass at cost, deferring the tax until the spouse sells or dies | Deferred |
| BC probate fee | $6 per $1,000 from $25,000 to $50,000 and $14 per $1,000 above $50,000 (Probate Fee Act) | The estate |
The capital gains inclusion rate remains one-half. A planned increase was cancelled on March 21, 2025 (Prime Minister’s announcement).
A worked example
Say a widowed parent in Surrey dies leaving a house they lived in, a rental condo bought for $300,000 now worth $500,000, and a $200,000 RRIF, all to two children.
- The house: usually no tax, because of the principal residence exemption.
- The condo: a $200,000 gain, of which half ($100,000) is added to the parent’s final income.
- The RRIF: the full $200,000 is added to the final return, because it goes to adult children, not a spouse.
- Probate: the fee is based on the gross value of the estate’s BC assets, less mortgages registered against them.
The executor pays the income tax and the probate fee from the estate. The children then split what is left, and pay no tax on receiving it. The numbers above are an illustration; the estate’s accountant works out the actual tax.
Is the BC probate fee an inheritance tax?
People often call it “probate tax”, but it is a court fee on the value of the estate, charged when the executor applies for a grant. It is not charged on assets that pass outside the estate, such as property in joint tenancy or an RRSP with a named beneficiary. A $500,000 estate pays $6,450 plus the $200 filing fee. Use our probate fee calculator, and see which assets go through probate.
What the executor has to do about tax
- File the final return. It is due April 30 of the following year if death was between January and October, or 6 months after death if it was in November or December (CRA guide T4011).
- File any estate (T3) returns for income the estate earns after death.
- Ask for a clearance certificate with Form TX19 before the final distribution. Without one, “you may be personally liable for the amount of tax owed by the deceased” (T4011).
- Hold back enough to cover the tax until the certificate arrives.
See our guide on executor duties in BC.
Inheritances from outside Canada, and US property
- Inheritance from another country: receiving it isn’t taxable income in Canada. Income it earns after you receive it is. If you hold foreign property costing more than $100,000 in total, you may have to file Form T1135.
- US property: if the deceased owned US real estate or US shares, US estate tax rules may apply. Get cross-border tax advice early.
- Inherited property you later sell: your cost is generally its value at the date of death, so you are taxed only on any gain after that.
Mistakes I have seen
- Paying out the RRIF beneficiary in full while the estate is left with the tax bill on that RRIF and too little to pay it.
- Distributing everything before the clearance certificate, then getting a reassessment the executor has to pay personally.
- Assuming the house is tax-free when part of it was rented out, or it wasn’t the person’s main home every year.
- Calling the probate fee “tax” and leaving it out of the estate budget.
Frequently asked questions
Do I have to report an inheritance on my tax return?
No. The CRA lists most gifts and inheritances as amounts you don’t report. Report any interest, dividends or rent the inherited property earns after you receive it.
Why did I get a tax bill after my parent died?
The bill is usually the parent’s final-return tax, which the estate owes. A beneficiary is not personally liable for it in the ordinary case, but if the estate was paid out before the tax was settled, the CRA can look to the executor, and in some cases to beneficiaries, up to what they received.
Is there tax when a house is left to a child?
If it was the parent’s principal residence for every year they owned it, usually not. A rental or second property is taxed on the gain at death.
Is life insurance taxable to the beneficiary?
Life insurance proceeds paid on death are generally not taxable to the beneficiary.
Does BC have an estate tax?
No. BC charges probate fees under the Probate Fee Act, but it has no separate estate or inheritance tax.
What should I do right now?
If you are the executor, list each asset with its value at the date of death and whether it has a named beneficiary, then speak with the estate’s accountant about the final return before paying anything out.
Book a consultation with our probate lawyers in Surrey, Abbotsford or Vancouver for help with probate and the executor’s steps.
Ready to book? Open the booking form ↑
Related guides: TFSA, RRSP and life insurance on death · the final tax return and clearance certificate · debts after death
Sources (official)
- Amounts that are not reported or taxed, Canada Revenue Agency (modified September 17, 2026)
- Preparing Returns for Deceased Persons (T4011), Canada Revenue Agency
- Prime Minister cancels proposed capital gains tax increase (March 21, 2025)
- Probate Fee Act, BC Laws
This article is general information, not legal or tax advice for your situation. Speak to an accountant about the estate’s tax returns.