Published
Prabhpreet Kaur Sangha is a lawyer at Lawgical Law Corporation, called to the BC bar in 2019, and a member of the Law Society of British Columbia.
Updated November 12, 2026: IRCC’s super visa document requirements checked that day.
The rule: private health insurance valid at least 1 year from entry, covering health care, hospitalization and repatriation, with at least $100,000 in coverage.
Who can sell it: a Canadian insurer, or an insurer outside Canada approved by the Minister.
Why a lawyer: insurance is one of four parts the officer weighs, and a policy that technically fails can sink an otherwise strong file. Why a lawyer
Our immigration lawyers
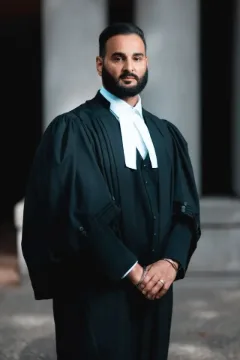 Sundeep S. GrewalBarrister and Solicitor
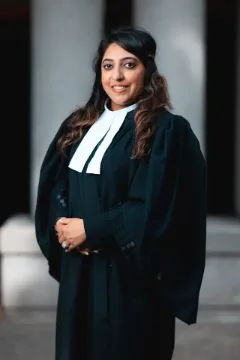 Prabhpreet Kaur SanghaBarrister and Solicitor
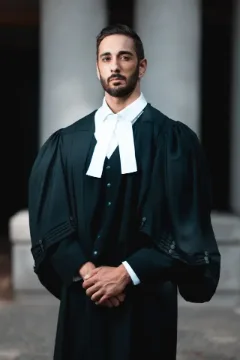 Pardeep S. GrewalBarrister and Solicitor
About our lawyers
Sundeep S. Grewal founded Lawgical Law Corporation and argues immigration cases at the Immigration and Refugee Board and the Federal Court of Canada.
Prabhpreet Kaur Sangha focuses on refugee claims, immigration appeals, inadmissibility, detention reviews and Federal Court cases, and has presented at Continuing Legal Education seminars and the National Immigration Conference.
Pardeep S. Grewal is an immigration and estates lawyer known for clear communication and practical strategy.
Every super visa applicant must have private health insurance, and it’s a common reason for refusal. IRCC requires a policy from a Canadian insurance company or an insurer outside Canada approved by the Minister. It must be valid for at least one year from the date of entry, cover health care, hospitalization and repatriation, and provide at least $100,000 in coverage. It can be paid in full or in instalments with a deposit, but a quote isn’t accepted. The policy must be valid for each entry and available for a border officer to see. Families often buy a policy first and check the rest of the application later. It works better the other way round.
Lawgical Law Corporation, an immigration law firm in Surrey, Abbotsford and Vancouver, BC, reviews super visa applications, including insurance, before filing and challenges refusals; this guide is by Prabhpreet Kaur Sangha.
Leave your details and our team will contact you to arrange a time with a lawyer. Or call (778) 598-3785.
Thank you, we have your request
A member of our team will contact you to arrange a time. If your matter is urgent, call us at (778) 598-3785, Monday to Friday, 9:00 am – 5:00 pm.
What the policy must have
| Requirement | Detail |
|---|---|
| Insurer | A Canadian insurance company, or an insurer outside Canada approved by the Minister |
| Length | At least 1 year from the date of entry |
| Coverage | Health care, hospitalization and repatriation |
| Amount | At least $100,000 |
| Payment | Paid in full, or in instalments with a deposit; quotes aren’t accepted |
| At the border | Valid for each entry and available for the officer to review |
What to check before you buy
- That the insurer itself meets IRCC’s rules, not just the seller or broker.
- That the start date matches the planned entry, and the policy runs a full year from then.
- That pre-existing conditions are dealt with, especially if the parent has a known health issue.
- That the proof of payment matches what IRCC accepts: a paid policy or a deposit with instalments.
On later entries
Because the policy must be valid for each entry, a parent who travels home and comes back may need to show current coverage at the border.
Why have a lawyer review the file, not just the policy?
One lawyer, one file, every step:
- checking the whole application, including the insurance, before filing;
- making sure the policy matches the entry date and the officer can verify it;
- dealing with any medical concerns that affect coverage;
- taking a refusal to the Federal Court where the officer misread the policy.
Insurance is only one of the four things the officer weighs. A lawyer looks at how it fits with the income, the medical exam and the ties at home, so the whole file holds together.
Immigration lawyers are members of a provincial law society (in our case, the Law Society of British Columbia), and only a lawyer can take a refusal to the Federal Court. An immigration consultant cannot file or argue it there.
Mistakes I have seen
- Sending a quote instead of a paid policy or deposit.
- Buying from a foreign seller whose insurer isn’t approved.
- A start date that doesn’t match the planned arrival.
Frequently asked questions
Can we pay monthly?
Yes. IRCC accepts instalments with a deposit, but not a quote.
Does the policy have to be from a Canadian company?
No. It can also be from an insurer outside Canada approved by the Minister.
What if my parent has a pre-existing condition?
Check the policy’s terms carefully, and get advice: the medical exam and the insurance should tell a consistent story.
What should I do right now?
Hold off on buying the policy until the income and ties evidence are ready, then confirm the insurer, the start date and the payment proof together.
Book a consultation with our immigration lawyers in Surrey, Abbotsford or Vancouver, or online from anywhere.
Ready to book? Open the booking form ↑
Sources (official)
- IRCC: Super visa, get your documents ready (modified February 10, 2025)
- IRCC: Super visa eligibility (modified July 6, 2026)
This article is general information, not legal advice. Every case depends on its own facts.