Published
Pardeep S. Grewal is a lawyer at Lawgical Law Corporation, called to the BC bar in 2024, and a member of the Law Society of British Columbia.
Updated November 11, 2026: the Wills, Estates and Succession Act (ss. 84, 85, 87, 96, 97), the Insurance Act and the Limitation Act, with the court decisions cited below, checked that day.
Which law: RRSPs, RRIFs, TFSAs and pensions fall under WESA Part 5; life insurance falls under the Insurance Act.
Common disputes: a will that tries to change the beneficiary; an irrevocable designation later changed; a separation agreement promising to keep a spouse as beneficiary; capacity or undue influence.
Deadline: generally 2 years (Limitation Act).
The lawyers who handle these estate files
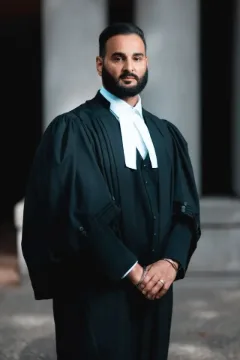
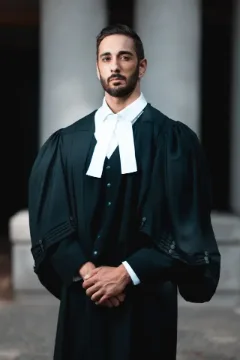
About our lawyers
Sundeep S. Grewal founded Lawgical Law Corporation and practises probate, estate litigation and immigration. He has represented clients in the Provincial and Supreme Courts of British Columbia, from chambers applications to contested trials.
Pardeep S. Grewal is a probate, estates and immigration lawyer known for clear communication and practical strategy.
Money from life insurance, RRSPs, RRIFs, TFSAs and pensions usually goes straight to the named beneficiary, outside the will. Disputes arise when someone says the wrong person is named. The most common reasons: the deceased tried to change the beneficiary in their will without referring to the plan clearly enough; an earlier designation was irrevocable and couldn’t be changed without the beneficiary’s consent; a separation agreement required the deceased to keep a former spouse as beneficiary; or the change was made when the deceased lacked capacity or was under someone’s influence. RRSPs, RRIFs, TFSAs and pensions are governed by Part 5 of WESA, and life insurance by the Insurance Act. The usual limitation period is two years.
Lawgical Law Corporation, a probate and estate litigation law firm with offices in Surrey, Abbotsford and Vancouver, BC, acts in disputes over insurance and registered plan beneficiaries; this guide is by Pardeep S. Grewal.
Leave your details and our team will contact you to arrange a time with a lawyer. Or call (778) 598-3785.
Thank you, we have your request
A member of our team will contact you to arrange a time. If your matter is urgent, call us at (778) 598-3785, Monday to Friday, 9:00 am – 5:00 pm.
The formal rules
- Benefit plans (WESA Part 5): a designation, change or revocation must be in writing and signed by the person or at their direction. It can’t change a designation that is irrevocable (WESA s. 85(2)).
- Designations in a will: only effective if they relate “expressly” to a benefit plan, generally or specifically (s. 85(2)(b)(i)). A residue clause leaving “all my assets” or “bank accounts” isn’t a designation.
- Revoking a will also revokes a designation made in it (s. 97(2)).
- Life insurance: a designation can be made by declaration, including in a will; a general reference to “all insurance policies on my life” will likely be enough, though listing the policy is better.
- Attorneys and committees can’t make or change a designation without court authorization, with a narrow exception (s. 85(3)).
Types of dispute
| Dispute | The question |
|---|---|
| Will vs plan | Did the will refer expressly enough to the plan or policy to change the beneficiary? |
| Irrevocable designation | Was the earlier designation validly irrevocable? If so, a later change without consent is invalid |
| Separation agreement | A covenant to keep a spouse as beneficiary can be treated like an irrevocable designation, or support damages or a trust |
| Capacity or undue influence | Was the change made freely, by someone who understood it? |
| Resulting or constructive trust | Should the beneficiary hold the money for someone else, such as the estate? |
Some examples discussed in the CLE manual:
- A will’s general revocation of “all former Wills and Testamentary dispositions” did not revoke an RRSP designation, because it didn’t show a clear intention to do so (Bottcher Estate, 1990 CanLII 710 (BC SC)). This is now reflected in WESA s. 97(1).
- Where a deceased wrote “irrevocable” on a designation form and gave it to the insurer’s agent, a later designation to a new partner was invalid (Manufacturers Life Insurance Co. v. Dahl, 2005 BCSC 1881).
- A covenant in a separation agreement to keep a spouse as beneficiary was held “tantamount to an irrevocable designation” (Fraser v. Fraser, 1995 CanLII 1594 (BC SC)). The Supreme Court of Canada has also imposed a constructive trust for a former spouse deprived of insurance proceeds she was contractually entitled to (Moore v. Sweet, 2018 SCC 52).
The deadline
The basic two-year limitation period applies (Limitation Act). For claims that the money is held in trust, the clock starts when the claimant becomes fully aware of the facts and that a court proceeding is appropriate (s. 12(2)). Because insurers and plan administrators pay out quickly, send a written notice of your claim to the insurer or plan administrator right away.
Mistakes I have seen
- Assuming a new will automatically changed the RRSP or insurance beneficiary.
- Waiting until the insurer has paid out before raising the claim.
- Overlooking an old separation agreement that required a designation to stay in place.
Frequently asked questions
Can a will change an RRSP beneficiary in BC?
Yes, if it refers expressly to the plan, generally or specifically, and the earlier designation wasn’t irrevocable. A general gift of “everything” doesn’t.
Can I stop the insurer paying out?
Notify the insurer in writing of the dispute immediately. A court order may be needed to hold the money pending the outcome.
Is the money part of the estate?
Not if a living beneficiary is validly named. It is paid to the estate only if the estate is named, or no named beneficiary survives.
What should I do right now?
Get copies of the current and past designation forms and any will or separation agreement that mentions the plan, then write to the insurer or administrator about your claim.
Book a consultation with our estate litigation lawyers in Surrey, Abbotsford or Vancouver.
Ready to book? Open the booking form ↑
Sources
- Wills, Estates and Succession Act (ss. 84, 85, 87, 96, 97), BC Laws
- Limitation Act (s. 12), BC Laws
- Bottcher Estate, 1990 CanLII 710 (BC SC); Manufacturers Life Insurance Co. v. Dahl, 2005 BCSC 1881; Fraser v. Fraser, 1995 CanLII 1594 (BC SC); Moore v. Sweet, 2018 SCC 52, as discussed in CLE BC, Estate Disputes in British Columbia: A Litigator’s Guide, chapter 14
This article is general information about BC law, not legal advice for your situation.